When a PE-backed healthcare platform needs to outsource accounting services, it is almost never because the team is not working hard enough. It’s because the accounting infrastructure they inherited from acquired practices was never originally built with the intention to bolt it onto what a PE sponsor actually needs.
Most bolt-on acquisitions arrive with their own chart of accounts, their own systems, and their own version of “how we close the books.” That is fine for a standalone practice. It is a serious structural problem for a platform trying to produce consolidated, board-ready financials across five, ten, or fifteen entities on a PE timeline.
For healthcare platforms managing significant multi-entity growth, that decision is increasingly urgent. The platforms that close their books cleanly and present accurate board packages are those with accounting functions built for complex consolidation from day one.
What You’ll Learn
• Why the accounting infrastructure inherited from acquired healthcare practices almost always fails at platform reporting level, and what the structural fix looks like
• What PE sponsors actually expect in a monthly board financial package, and the close timeline they consider non-negotiable
• How post-acquisition accounting integration works in practice, from chart-of-accounts standardization to system migration
• The five specific reasons PE-backed healthcare platforms move to an outsourced accounting model, and what each one solves
• What to look for in an outsourced accounting partner if your platform operates across multiple healthcare entities
Table of Contents
1. What “Board-Ready Financials” Actually Means for a PE-Backed Healthcare Platform
2. Why the Accounting Setup You Inherited From Your Acquisitions Cannot Meet That Standard
3. What Does Post-Acquisition Accounting Integration Actually Look Like?
4. Five Reasons PE-Backed Healthcare Platforms Outsource Their Accounting Function
5. What to Look for in an Outsourced Accounting Partner
6. Questions PE-Backed Healthcare CFOs Ask Before Making the Switch
What “Board-Ready Financials” Actually Means for a PE-Backed Healthcare Platform
Board-ready financials are structured and delivered to your PE sponsor’s exact standard; far beyond what individual practice teams are used to providing.
A proper monthly board financial package for a PE-backed healthcare platform typically includes:
• A consolidated P&L across all entities, with intercompany eliminations applied correctly
• A balance sheet and cash flow statement at both the entity and platform level
• Management fee allocations, ownership-adjusted P&Ls, and any intercompany transactions resolved before the package goes out
• Lender covenant reporting and any KPI tracking your sponsor requires
• The whole package delivered by an agreed date of the month following close
Delivering by a fixed date each month is a firm expectation, as sponsors run investment committee cycles, lender reporting obligations, and portfolio-level analysis on that cadence. A package that lands late is useless for the decisions that were already made without it.
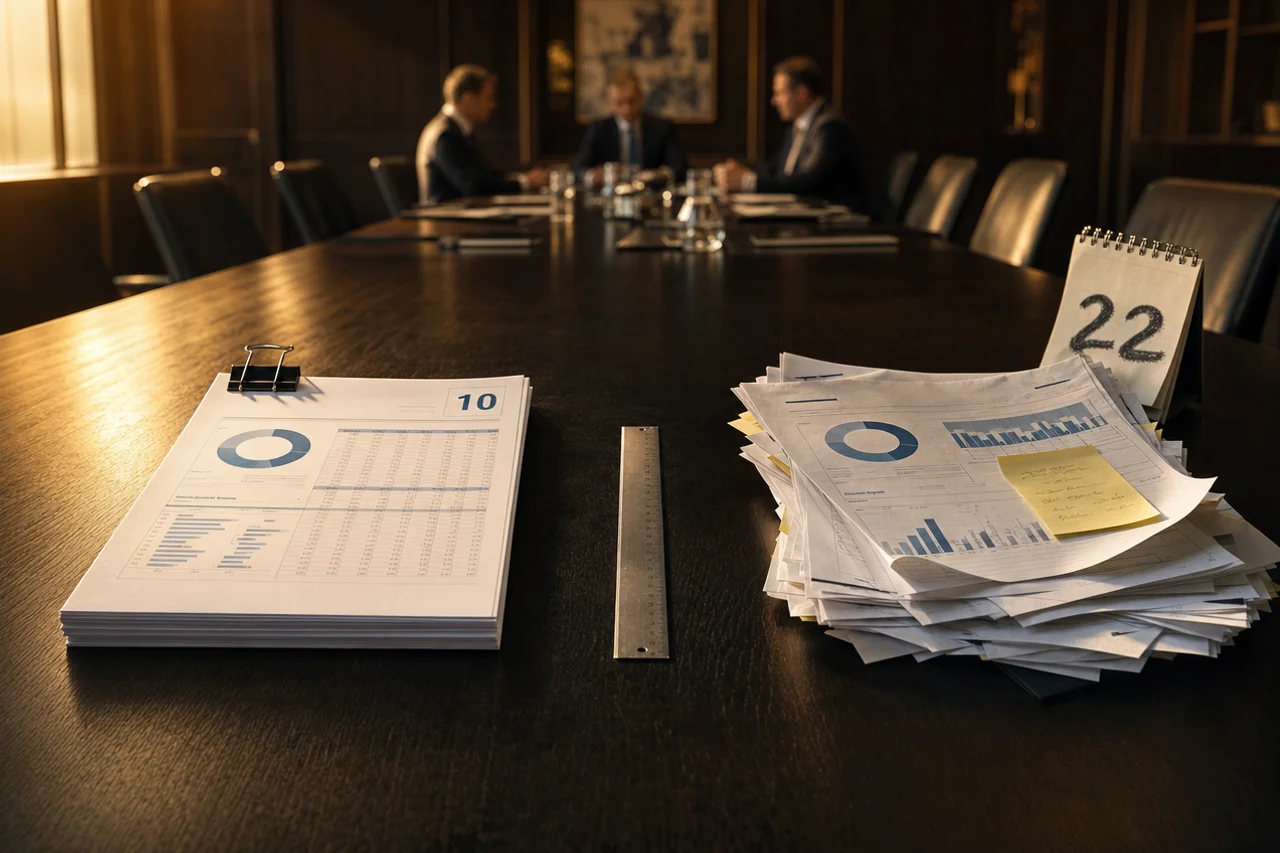
PE-backed healthcare platforms fail their board reporting deadlines not because of a staffing problem, but because the accounting infrastructure inherited from acquired practices was never built to consolidate across entities on a PE timeline.
Why the Accounting Setup You Inherited From Your Acquisitions Cannot Meet That Standard
Every acquisition your platform closes brings a new accounting problem. The practice you acquired was running its own chart of accounts, its own version of QuickBooks or another system, and its own close process that probably finished sometime around the 22nd or later.
Here is what that actually looks like at platform level:
• Inconsistent charts of accounts: When five acquired practices use five different account structures, there is no clean way to roll them up. Someone is manually mapping accounts in a spreadsheet every month, and that spreadsheet is always slightly wrong.
• No consolidation infrastructure: Intercompany eliminations, management fee allocations, and ownership-adjusted P&Ls require a system and a process built for consolidation. A QuickBooks instance designed for a single practice does not have it.
• Staff built for standalone operations: The bookkeeper who came with the acquisition is good at what they were hired to do. What they were hired to do was close one practice’s books in isolation, not contribute to a platform-level reporting package.
• System fragmentation: Multiple EHRs, different practice management platforms, and accounting systems that do not connect to each other mean data is re-keyed at every step. Reconciliation is always off by something.
For per-location profitability reporting to work at platform level, every entity in the structure needs to report on the same basis, on the same timeline, into the same consolidation infrastructure. What most platforms inherit is the opposite of that.
What Does Post-Acquisition Accounting Integration Actually Look Like?
Post-acquisition accounting integration is the work of taking a newly acquired practice’s financial infrastructure, which was built for one purpose, and rebuilding it to function inside a multi-entity platform structure.
Done well, it follows a clear sequence:
1. Chart-of-accounts standardization: Map the acquired practice’s accounts to the platform’s master chart of accounts. Resolve conflicts, eliminate redundancies, and establish a single structure every entity reports into.
2. System migration: Migrate historical data from the acquired practice’s system into the platform’s accounting system. This requires experience, because data that looks clean in one system rarely arrives clean in another.
3. Intercompany setup: Identify all intercompany transactions, management fees, and shared-cost allocations. Set up the eliminations structure so they clear properly in consolidation.
4. Close process alignment: Establish the acquired practice’s close timeline, task ownership, and deliverable dates to match the platform’s reporting cadence.
5. Reporting validation: Run a parallel close for at least one period to confirm the consolidated output matches expectations before the sponsor sees it.
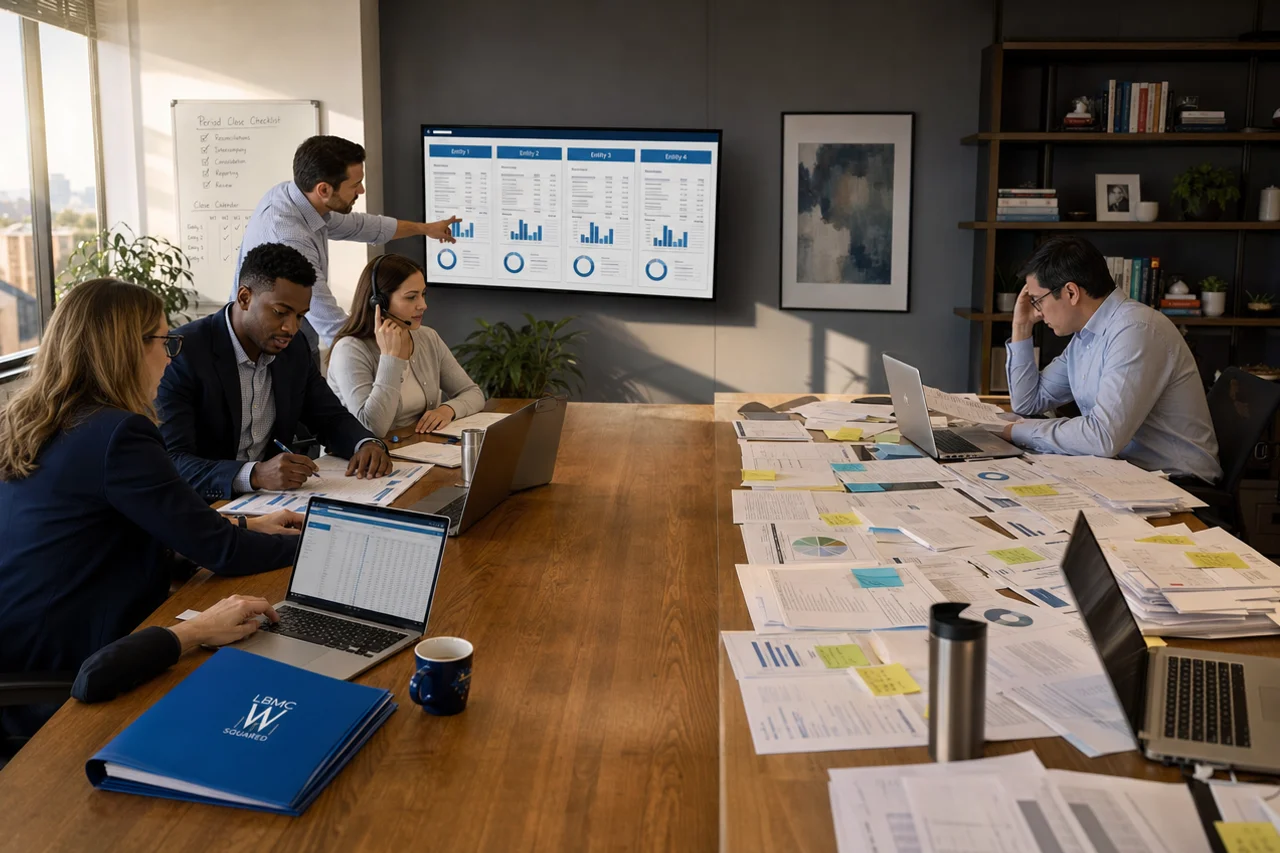
Integrating acquired practices requires unraveling complex financial historical data to simplify it and ensure newly onboarded entities align seamlessly with platform-wide accounting standards.
That is what post-acquisition integration actually requires: someone who has done it enough times to move fast and not break things. With the right outsourced accounting partner and a clear migration plan, the initial consolidated reporting structure can be in place within weeks of an acquisition close, not quarters.
Five Reasons PE-Backed Healthcare Platforms Outsource Their Accounting Function
PE-backed healthcare platforms move to an outsourced model to fix structural problems that internal hires cannot solve quickly or cost-effectively.
Here are the five reasons that drive the decision:
1. Meeting Sponsor Reporting Deadlines Consistently
As an example, the 10th-of-the-month deadline is not moveable. An outsourced accounting firm that specializes in PE-backed healthcare platforms builds its entire close process around an agreed upon cadence. Internal teams assembled from acquired-practice staff typically cannot match it without significant investment in process redesign.
2. Absorbing Acquisitions Without Adding Internal Headcount Each Time
Every new acquisition adds complexity. With an outsourced model, that complexity is absorbed by the firm, not by a new internal hire who then needs to be onboarded, managed, and retained.
Outsourcing the accounting function gives a growing healthcare platform a team that absorbs each new acquisition without adding to internal headcount, the complexity scales with the firm, not with the org chart.
3. Producing Audit-Ready Financials for Exit
The difference between audit-ready and audit-hopeful is a structural accounting problem. Audit-ready means the books are reconciled, documented, and maintained to the standard an external auditor or quality-of-earnings reviewer expects to find them. Getting there requires consistent process and genuine technical depth across every entity in the platform.
4. Standardizing Financial Infrastructure Across Entities With Different Histories
Each acquired practice has a different financial history. Standardizing the chart of accounts, the close process, and the reporting format across all of them is a one-time implementation problem, but it requires someone who knows exactly what the end state needs to look like and can execute the migration without disrupting live operations.
5. Accessing Healthcare Accounting Depth That an Internal Hire Rarely Matches
Multi-entity healthcare consolidation requires a nuanced understanding of payer structures, intercompany eliminations, and complex reporting standards. Building this capability internally often takes years of trial and error. Partnering with a specialist firm allows platforms to immediately leverage two decades of dedicated operational experience to diagnose and resolve complex consolidation issues efficiently.
A healthcare accounting firm like LBMC W Squared, that has spent 20 years inside the complexity of multi-entity medical groups, will diagnose and fix a consolidation problem faster than any generalist hire, because they have seen every version of it before.
What to Look for in an Outsourced Accounting Partner for a PE-Backed Platform
Not every firm that advertises outsourced healthcare accounting can operate at PE speed and standard. Here is what to evaluate before you make a decision.
| Evaluation Criteria | What to Look For | Red Flag |
| Healthcare vertical depth | 10+ years of multi-entity healthcare accounting | General accounting firms that “also serve healthcare” |
| Post-acquisition integration | Documented track record of fast chart-of-accounts and system migrations | Vague claims about onboarding capability |
| System migration capability | Experience moving data from QuickBooks, multiple EHRs, and practice management platforms | Firms that require you to already be on their preferred system |
| Team-based delivery model | Dedicated team with no single point of failure | One assigned accountant with no backup structure |
| Reporting cadence commitment | Contractual close and delivery timeline, not a general estimate | “We’ll do our best to hit the 10th” |
| Sponsor reporting experience | Familiarity with PE board packages, lender covenants, and QoE preparation | No prior PE-adjacent client experience |
The team model matters more than most CFOs initially expect. When your platform closes its next acquisition and the close timeline tightens, you need a team that already knows your structure, not one person who is now managing twice the volume.
LBMC W Squared operates with a team approach across every engagement. There’s not one single point of failure. That consistency translates directly to the reporting reliability PE sponsors require. And the results compound over time and the team’s knowledge of the platform deepens with every reporting cycle.
Key Takeaways
• Board-ready financials for a PE-backed platform mean a consolidated package across all entities, with intercompany eliminations applied, delivered by a fixed date, every month. Most acquired-practice accounting setups cannot hit that standard without a structural fix.
• Post-acquisition integration is a defined process: chart-of-accounts standardization, system migration, intercompany setup, close alignment, and reporting validation. With an experienced team, it takes weeks, not months.
• The five core reasons platforms outsource: sponsor reporting deadlines, acquisition absorption, exit readiness, infrastructure standardization, and healthcare accounting depth that generalist hires rarely match.
• Evaluate partners on healthcare depth, integration track record, system migration capability, team model, and the specificity of their reporting commitments.
• The cost of not outsourcing shows up in missed board deadlines, failed quality-of-earnings reviews, and a close process that falls further behind with every acquisition.
Questions PE-Backed Healthcare CFOs Ask Before Making the Switch
Why do PE-backed healthcare companies outsource their accounting?
The accounting setups inherited from acquired practices were built for standalone operations, not platform-level consolidation. An outsourced specialist firm provides the infrastructure, team depth, and reporting cadence a PE sponsor requires, without the time and cost of building it internally after every acquisition. For most platforms, it is faster and more reliable than any internal-build approach.
What should a monthly board financial package include for a PE-backed healthcare platform?
It should include a consolidated P&L across all entities with intercompany eliminations applied, a balance sheet, a cash flow statement, management fee allocations, and any lender covenant or KPI reporting the sponsor requires. The full package should be delivered by an agreed date of the month following close. Anything later than that misses the decision cycles it is supposed to inform.
How long does it take to integrate a newly acquired practice’s financials into a platform structure?
With the right outsourced accounting partner and a clear system migration plan, chart-of-accounts standardization and initial consolidated reporting can typically be achieved within weeks of acquisition close, not months. Speed here depends almost entirely on the firm’s experience with post-acquisition integration in healthcare, and on how quickly they can move data from the acquired practice’s systems into the platform’s accounting infrastructure.
What is the difference between audit-ready and audit-hopeful financials?
Audit-ready financials are structured, reconciled, and documented to the standard an external auditor or quality-of-earnings reviewer expects to find them. Audit-hopeful means the books have not been kept to that standard and would require significant cleanup before any formal review. That cleanup is costly and time-sensitive at the point of exit, which is precisely the wrong moment to discover it.
Can an outsourced accounting team handle multiple healthcare entities simultaneously?
Yes, and for PE-backed platforms this is the primary reason to outsource. A specialist firm with a team-based delivery model manages consolidation across all entities as a standard function. An internal accounting hire would need to be duplicated at each new entity as the platform grows, with no guarantee of consistent process or reporting quality across the structure.
How do I evaluate an outsourced accounting firm for a PE-backed healthcare platform?
Look for documented healthcare vertical depth, a track record of post-acquisition integration work, the ability to migrate data from multiple systems quickly, a team-based delivery model with no single point of failure, and a firm that can commit to a specific close and delivery timeline rather than a general estimate. Ask for examples from platforms of similar complexity, and ask specifically how they handle the first 30 days after a new acquisition closes.
Book a Conversation
If your current close process is not meeting sponsor expectations, we should talk. LBMC W Squared has been working inside the complexity of multi-entity healthcare accounting for 20 years. We know what board-ready financials require, we know how to integrate a newly acquired practice fast, and we know what the infrastructure needs to look like to hold up through an exit.